
How to Handle Insurance Pressure After a Crash
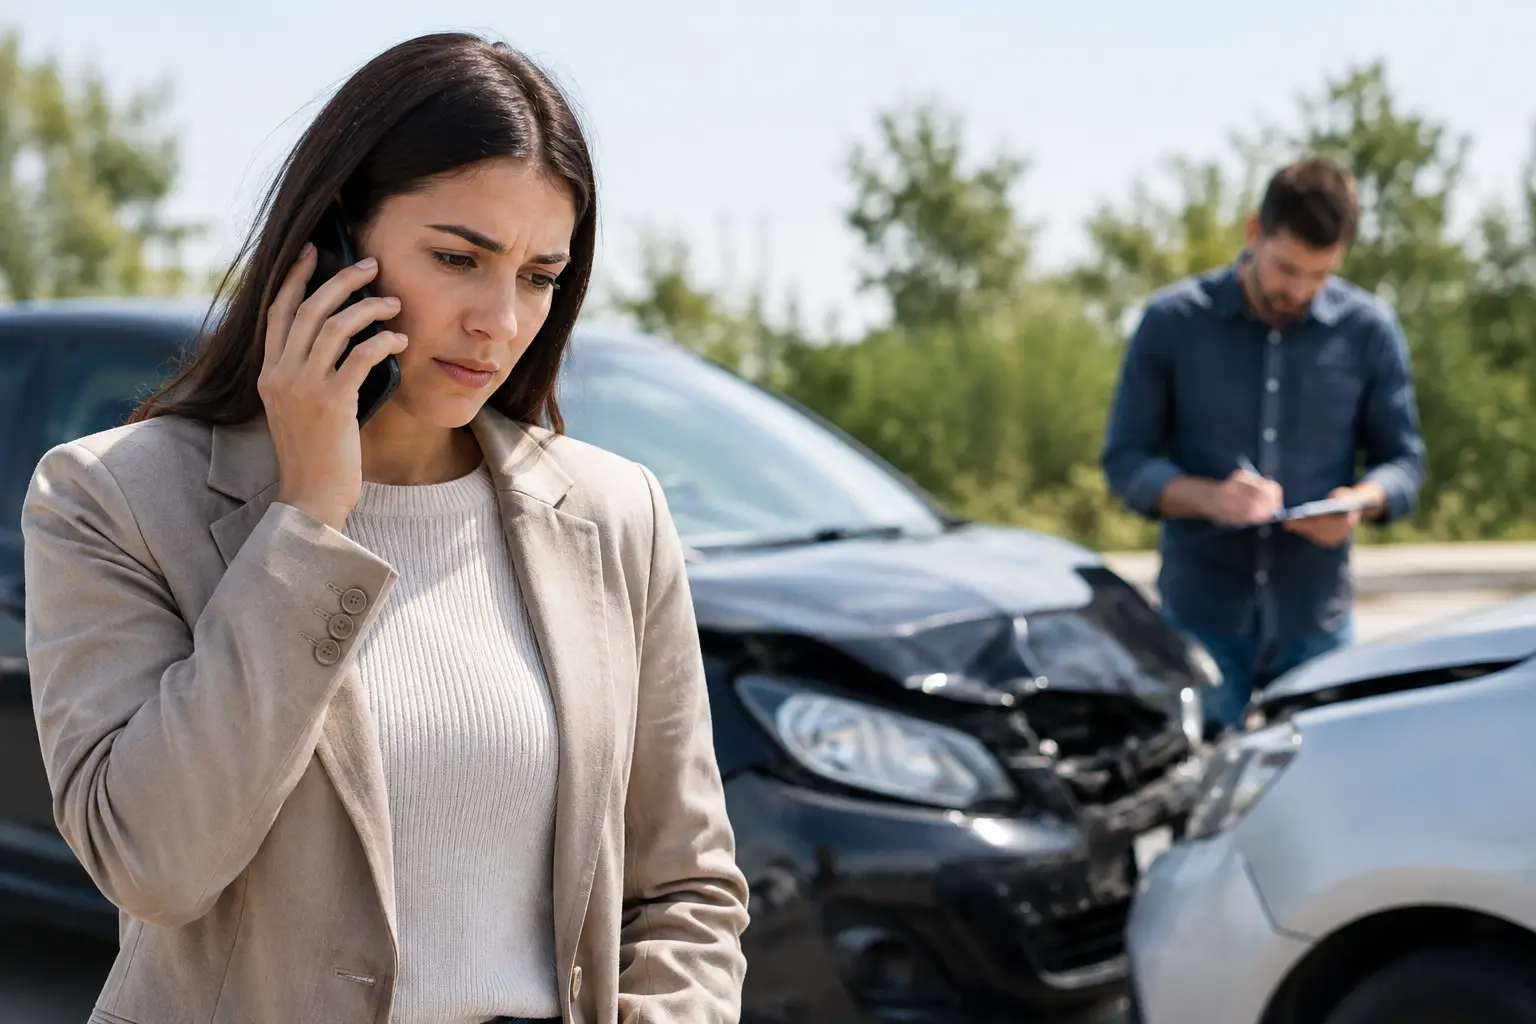
The calls may start before you have had time to absorb what happened. An insurance representative may sound sympathetic, ask for a recorded statement, or offer money quickly while you are still in pain and worried about expenses. Knowing how to handle insurance pressure after a crash can protect both your health and your ability to pursue fair compensation.
After a serious collision, you do not have to make major decisions on the insurer’s timetable. Their goal is often to close the matter for as little as possible. Your goal should be to understand the full impact of your injuries, preserve the evidence, and avoid saying or signing something that weakens your position.
Why Insurance Pressure Starts So Quickly
Insurance companies often begin their investigation right away. They may contact you while you are at home, at a medical appointment, or trying to arrange transportation and care for your family. A quick call can feel helpful, especially when bills are already arriving. But early conversations can also shape how the insurer evaluates fault, injuries, and the value of your losses.
The representative may ask seemingly ordinary questions: How are you feeling? What were you doing just before the collision? Have you returned to your normal routine? Those answers can later be used to argue that your injuries are not serious, that you were partly responsible, or that you recovered faster than you actually did.
This does not mean you need to be hostile. It means you should be careful. You can be polite while limiting the information you provide until you understand your rights and the full scope of your situation.
What to Do When an Insurer Calls
Start by getting the caller’s name, company, phone number, and claim reference number. Tell them you are not ready to discuss the details of the crash. You can say that you are focusing on your recovery and will respond after you have had time to review the situation.
Avoid guessing about facts. If you do not know the answer to a question, do not fill in the gap. Pain and injuries can change over days or weeks, and it is common for the full effects of a collision to become clearer after the initial shock has passed.
Do not agree to a recorded statement simply because the insurer requests one. You may have a duty to cooperate with your own insurance carrier under your policy, but the other driver’s insurer does not get to control the conversation. A personal injury attorney can help you understand what information must be provided and how to respond without damaging your claim.
Be Careful With Casual Language
People often say “I’m fine” as a reflex. After a crash, that phrase can be misleading. You may be trying to be courteous, but an insurer can treat it as evidence that you were not hurt.
Stick to the facts. It is reasonable to say that you are seeking medical evaluation, following your care providers’ recommendations, or are not prepared to discuss your condition in detail. Do not minimize your pain to make the conversation easier.
Do Not Accept a Fast Settlement Without Looking Closer
A quick settlement offer can be tempting when income has been disrupted and expenses are mounting. But once you accept and sign a release, you may give up the right to seek additional compensation later, even if your condition worsens or new costs appear.
The first offer may not account for the complete picture. Depending on the facts, a crash claim can involve more than current medical expenses. It may include future treatment needs, lost income, reduced ability to work, pain, emotional distress, and the disruption the injury has caused in daily life.
The right decision depends on the circumstances. Some matters can be resolved efficiently when fault is clear and the losses are fully known. Others need more time because injuries are still being evaluated, the other side disputes responsibility, or several insurance policies may apply. Pressure to settle quickly is not a reason to settle before you are ready.
Protect Evidence Before It Disappears
Insurance pressure is easier to resist when you have clear information supporting your side. Save every document connected to the collision and your injuries. Keep photos of the vehicles, roadway, visible injuries, and anything else that shows what happened. Preserve receipts, medical records, invoices, and written communications from insurers.
It also helps to keep a simple personal record of how the injuries affect you. Note missed work, interrupted sleep, help you need at home, activities you cannot do, and changes in your symptoms. These details can be difficult to remember months later, yet they can matter when explaining the real impact of the crash.
If there were witnesses, their memories may fade. Video from nearby businesses, homes, or traffic cameras can also be lost if no one acts quickly. An attorney can take steps to identify and preserve available evidence while you focus on your recovery.
Watch for Common Insurance Tactics
Not every insurer representative acts improperly, but you should recognize tactics that can put pressure on an injured person. They may repeatedly call when you have already said you need time. They may suggest that an offer is final or about to expire. They may ask you to authorize broad access to years of private medical information.
Broad authorizations deserve special attention. The insurer may seek information unrelated to the crash in an effort to argue that your symptoms came from another source. Some prior health history can be relevant, but that does not mean an insurer should have unrestricted access to every private record.
You should also be cautious about discussions of blame. Texas uses a proportionate-responsibility system. In many situations, an injured person may still recover damages if they were partly at fault, but the amount can be reduced by their share of responsibility. Insurers know this and may look for statements that shift more blame onto you than the evidence supports.
When You Should Speak With a Lawyer
Legal help can be especially valuable when the crash caused significant injuries, the insurer is disputing fault, multiple vehicles were involved, or the available coverage is unclear. It can also make sense when an insurer is pushing for a statement, requesting extensive records, or presenting a settlement before you know the long-term cost of your injuries.
A plaintiff-side personal injury attorney can handle insurer communications, investigate the collision, organize evidence, calculate losses, and negotiate from a position of preparation. That changes the dynamic. Instead of managing calls while you are in pain or trying to support your family, you have someone protecting your interests and demanding that the insurer take the evidence seriously.
At Feizy Law Office, injured Texans receive direct guidance through the difficult parts of an injury claim, from early evidence collection through negotiations with insurers. A conversation with an attorney can give you a clearer view of your options before you make an irreversible decision.
Keep Your Focus Where It Belongs
The days after a crash can feel chaotic. You may be dealing with physical pain, missed income, appointments, transportation problems, and calls that make you feel as though you need to decide everything immediately. You do not.
Take care of your health, keep your records, and give yourself room to understand what the collision has truly cost you. If insurance pressure continues, getting experienced legal support can help you move forward with confidence instead of accepting less simply because the insurer moved first.


About Post Author
